
Haphazard rollout of a mandated appraisal overhaul is disrupting closing costs, lender selection and turn times for mortgage brokers as limited participation undermines smoother adoption.
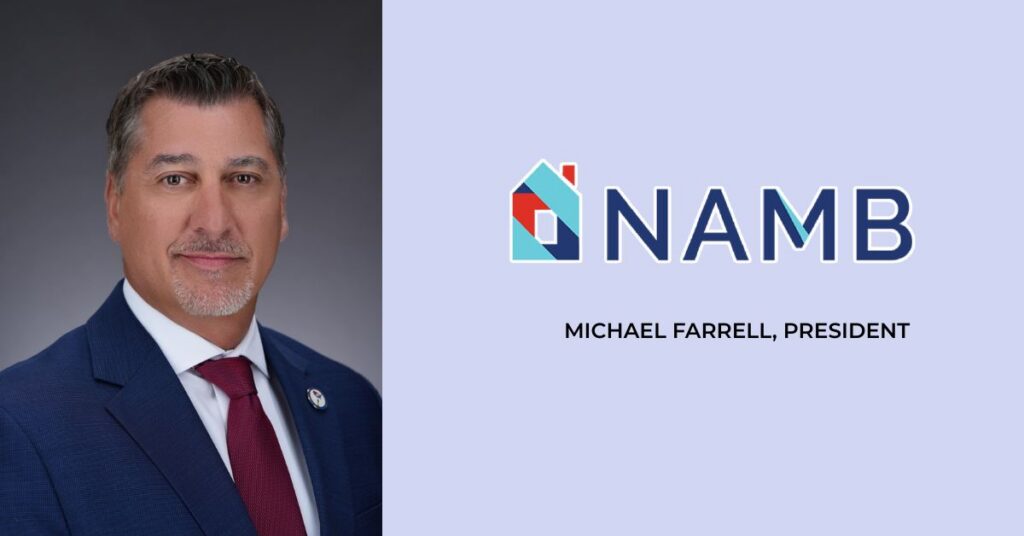
Michael Farrell, who took over as president of the National Association of Mortgage Brokers (NAMB) in early October, says playing the blame game does nothing to help consumers, who are ultimately bearing the cost of industry-wide dysfunction.
“It’s basically all roads lead to chaos,” explains Farrell, speaking with Scotsman Guide during an interview Tuesday. “From an originator standpoint, it’s delay. Delays cost money. Delays cost the consumer money.”
Mandatory adoption of Uniform Appraisal Dataset (UAD) 3.6 was initially scheduled for Nov. 2, until Fannie Mae and Freddie Mac announced a limited extension in late September. The government-sponsored enterprises (GSEs) pushed mandatory implementation to May 2027 — but only for lenders granted waivers.
Closing cost discrepancies and delays
Some large lenders are already selling loans to Fannie and Freddie using UAD 3.6 appraisals and have been since the GSEs began accepting loan files with the modernized appraisals on a limited basis last November.
Many other lenders, however, have delayed implementation until recently, creating bottlenecks as the UAD 3.6 deadline approaches. Appraisal software providers and field appraisers have also dragged their feet on implementation, experts say.
But with Fannie and Freddie creating a dual appraisal track until next spring, Farrell says lenders who no longer order appraisals under the previous framework, UAD 2.6, are likely to lose business to lenders who will still accept files supported by the older framework until the last second.
The number of field appraisers equipped to do UAD 3.6 is so limited at this point, says Farrell, that demand bottlenecks are driving up prices for modernized reports. While older appraisals are being priced at around $550, modernized reports may cost borrowers closer to $850.
UAD 3.6 appraisals will also likely be more expensive because the new reports require that appraisers train themselves on the new data fields and spend more time at the property. On the loan side, Farrell advises brokers to anticipate an extra three to five days in processing and delivery of UAD 3.6 reports.
“From a broker perspective, be very cautious which lender you’re using for your consumer,” Farrell cautions, saying selecting the wrong lender may increase appraisal costs for consumers and possibly result in delays.
In the latter instance, brokers are apt to find themselves quoting the wrong fee amounts to prospective borrowers, undermining their ability to be transparent and trustworthy loan advisers.
Farrell’s advice to mortgage brokers
Longer turn times need to be taken into consideration with mortgage rate locks, while expectations also need to be set by brokers for their borrowers and referral partners.
Lenders and brokers also have a duty to disclose fees on closing cost estimates as accurately as they can. Given how much of the origination process is outside of a broker’s control, Farrell says brokers should engage with lenders and wholesalers to understand which appraisals are being used and how to best communicate appraisal changes to borrowers.
“Best practices,” advises Farrell, “we’re going to be over-disclosing until we know what the exact cost is going to be based on the actual order that was placed.”
As a board member of NAMB and former chairman of its political action committee, Farrell has also sat on the advisory council of The Appraisal Foundation as appraisal modernization efforts have unfolded over the past few years. That foundation is authorized by Congress to establish and monitor appraisal industry standards.
While appraisers point fingers at software providers for delaying the UAD 3.6 rollout, Farrell says Fannie and Freddie lay blame at the feet of lenders for not engaging with modernization early enough. The learning curve involved in appraisal changes underway is ultimately too steep for any stakeholder to try to figure out at the last minute, he thinks.
“We believe that 3.6 is going to better Fannie and Freddie,” says Farrell, noting that the expanded data collected from field appraisers will “allow more opportunity for the utilization of a hybrid appraisal or an appraisal waiver.”