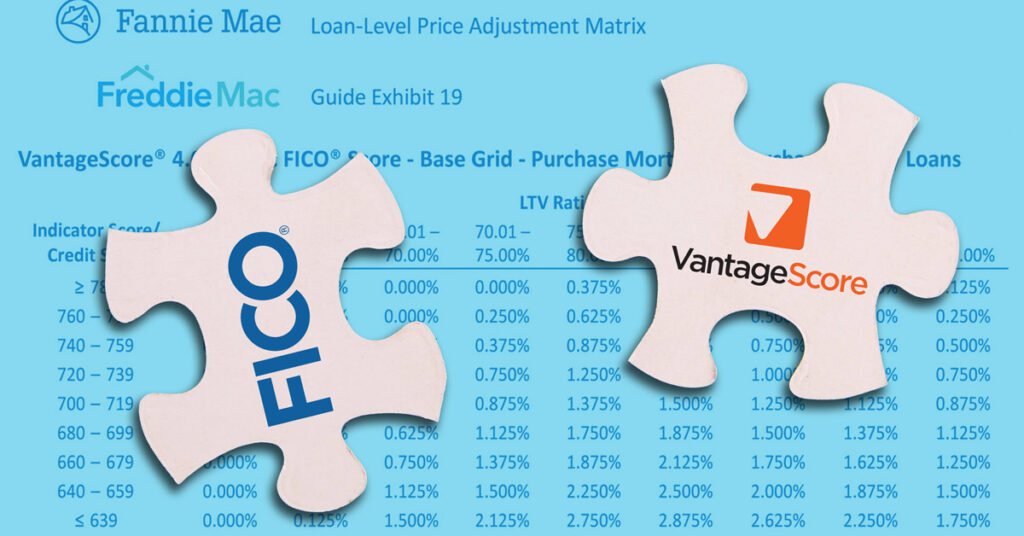
Mortgage lenders can now originate loans using either VantageScore 4.0 or Classic FICO credit scores without facing different Fannie Mae and Freddie Mac fees based on the scoring model used on an individual file.
Guidance published Wednesday by the government-sponsored enterprises (GSEs) said the new loan-level pricing adjustments (LLPAs) would take effect for mortgage loans and mortgage-backed securities (MBS) settled or issued on Oct. 1 or later.
“Credit fees will no longer be differentiated based on the credit score model with which the mortgage is delivered,” said Freddie Mac in a seller bulletin outlining the shift.
“When a lender elects to use VantageScore 4.0, they must request VantageScore 4.0 from each of the three credit repositories when ordering a new credit report,” Fannie Mae said in updated guidance.
Lenders can select either Classic FICO or VantageScore 4.0 for eligible loans, though the same model must be used for all borrowers on a single loan file. Lenders can only utilize FICO, however, for manually underwritten loans.
“Lenders must ensure the credit score model used for underwriting and pricing is accurately reflected in the loan data delivered to Fannie Mae and that all applicable credit score information is retained in the loan file,” Fannie added.
Bill Pulte, director of the Federal Housing Finance Agency (FHFA) that regulates Fannie Mae and Freddie Mac, previewed the LLPA changes in a social media post on Monday.
“Instead of two separate pricing grids, which makes zero sense, Fannie and Freddie are hereby moving to ONE PRICING GRID with VantageScore joining the existing FICO Classic pricing grid,” Pulte wrote.
A Fannie Mae spokesperson told Scotsman Guide on Thursday that the changes to the LLPA grid were based on market feedback.
“Removing separate pricing grids creates a consistent approach across both approved credit score models, supports lender choice, and is another step in our measured approach to advancing a modernized and competitive credit score framework while maintaining appropriate risk management and operational controls,” the spokesperson said in a statement.
The three national credit bureaus — Experian, Equifax and TransUnion — jointly developed VantageScore in 2006 to compete with FICO’s longstanding model across consumer credit markets.
Since Pulte became director of the FHFA in early 2025 and subsequently appointed himself board chair of Fannie and Freddie, he has fast-tracked credit score modernization efforts, including mainstreaming VantageScore adoption.
After launching a limited pilot program in April that enabled some of the country’s largest lenders to submit loans underwritten with VantageScore to Fannie and Freddie, the FHFA expanded availability to all GSE-approved lenders early in September.
While this week’s loan-level pricing changes are expected to accelerate adoption of VantageScore 4.0, the unified pricing grid does not eliminate differentiated risks between the scoring models for Fannie and Freddie, experts say.
LLPAs — which have historically been based on Classic FICO scores — are tiered to reflect variable collateral risks posed by borrowers with different scores, relative to secondary factors like loan-to-value ratios or occupancy type. Lenders typically recoup that fee from borrowers.
The extent to which LLPAs are purely actuarial is debated in the industry. Differences in default and prepayment performance, for example, remain uncertain across the two models.
But merging loan-level pricing for mortgages underwritten using VantageScore with the existing FICO framework nevertheless implies that the collateral risks undergirding the scoring models are commensurate.