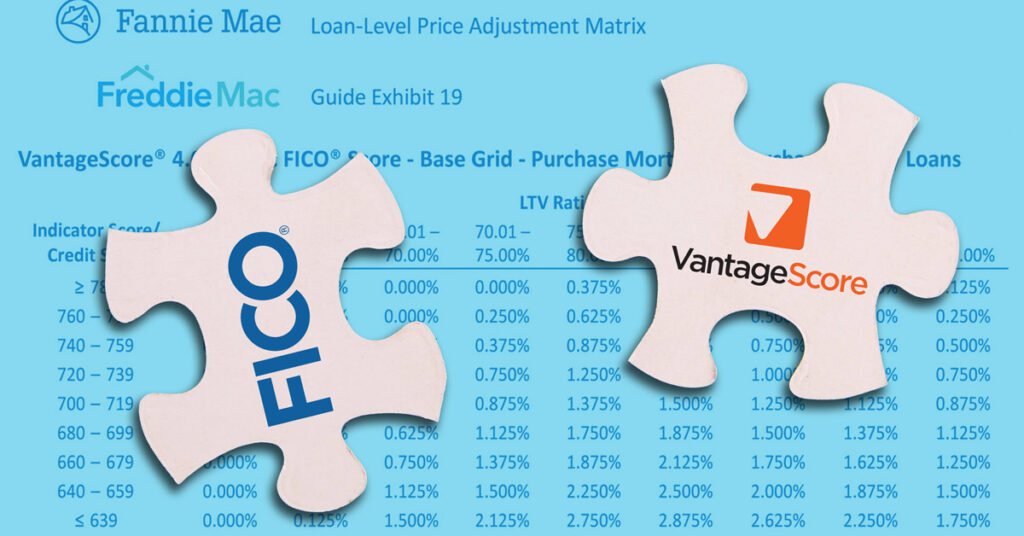
Mortgage lenders can now originate loans using either VantageScore 4.0 or Classic FICO credit scores without facing different Fannie Mae and Freddie Mac fees based on the scoring model used on an individual file.
Guidance published Wednesday by the government-sponsored enterprises (GSEs) said the new loan-level pricing adjustments (LLPAs) would take effect for mortgage loans and mortgage-backed securities (MBS) settled or issued on Oct. 1 or later.
“Credit fees will no longer be differentiated based on the credit score model with which the mortgage is delivered,” said Freddie Mac in a seller bulletin outlining the shift.
“When a lender elects to use VantageScore 4.0, they must request VantageScore 4.0 from each of the three credit repositories when ordering a new credit report,” Fannie Mae said in updated guidance.
Lenders can select either Classic FICO or VantageScore 4.0 for eligible loans, though the same model must be used for all borrowers on a single file. Lenders can still only use FICO, however, for manually underwritten loans.
“Lenders must ensure the credit score model used for underwriting and pricing is accurately reflected in the loan data delivered to Fannie Mae and that all applicable credit score information is retained in the loan file,” Fannie added.
Bill Pulte, director of the Federal Housing Finance Agency (FHFA) that regulates Fannie Mae and Freddie Mac, previewed the LLPA changes in a social media post on Monday.
“Instead of two separate pricing grids, which makes zero sense, Fannie and Freddie are hereby moving to ONE PRICING GRID with VantageScore joining the existing FICO Classic pricing grid,” Pulte wrote.
Fannie and Freddie cite ‘simplified’ pricing
A Fannie Mae spokesperson told Scotsman Guide on Thursday that the changes to the LLPA grid were based on market feedback.
“Removing separate pricing grids creates a consistent approach across both approved credit score models, supports lender choice, and is another step in our measured approach to advancing a modernized and competitive credit score framework while maintaining appropriate risk management and operational controls,” the spokesperson said in a statement.
The three national credit bureaus — Experian, Equifax and TransUnion — jointly developed VantageScore in 2006 to compete with FICO’s longstanding model across consumer credit markets.
Since Pulte became director of the FHFA in early 2025 and subsequently appointed himself board chair of Fannie and Freddie, he has fast-tracked credit score modernization efforts, including mainstreaming VantageScore adoption.
After launching a limited pilot program in April that enabled some of the country’s largest lenders to submit loans underwritten with VantageScore to Fannie and Freddie, the FHFA expanded availability to all GSE-approved lenders early in September.
A Freddie Mac spokesperson noted that the unified pricing matrix will help speed up adoption of the modernized score by simplifying pricing.
“This approach supports a more straightforward implementation path for sellers and market participants and supports broader credit score modernization efforts,” the spokesperson said in a statement.
Subsidized scores are underpricing risk
While this week’s pricing changes are expected to accelerate uptake of VantageScore 4.0, the new matrix does not eliminate differentiated risks between the scoring models for Fannie and Freddie, experts say.
“The net effect of this announcement is that use of VantageScore 4.0 has effectively been subsidized, as there is a tendency for borrowers to score higher using VantageScore’s methodology over Classic FICO and thus obtain better GSE pricing,” said Sam Valverde, nonresident fellow at the Urban Institute and former acting president of Ginnie Mae.
LLPAs — which have historically been based on Classic FICO scores — are tiered to reflect variable collateral risks posed by borrowers with different scores, relative to secondary factors like loan-to-value (LTV) ratios or occupancy type. Lenders typically recoup that fee from borrowers.
The extent to which LLPAs are purely actuarial is debated in the industry. Merging loan-level pricing for mortgages underwritten using VantageScore with the existing FICO framework implies that the collateral risks undergirding the scoring models are commensurate.
However, VantageScore confirmed in an email to Scotsman Guide that is not necessarily the case.
“A shared pricing grid does not mean that identical scores from different models necessarily represent identical mortgage risk,” said Tony Hutchinson, head of public affairs at VantageScore.
However, removing LLPA pricing differentials between VantageScore 4.0 and Classic FICO scoring models “brings pricing closer to the risk relationships observed in our historical mortgage analysis,” Hutchinson said, “while continued alignment to default risk can further strengthen consistent pricing for comparable borrowers.”
What those differences are between default and prepayment performance, for example, remain highly uncertain. Market participants are positioning their businesses to reflect the disparate risks.
“In particular, we recommend adjusting delinquency forecasts by LTV for loans using VantageScore 4.0, reducing the delinquency forecast by 20% for high LTV loans and increasing the forecast by 20% for low LTV loans,” said Andrew Davidson, CEO of Andrew Davidson and Co., an MBS advisory and analytics firm.
Davidson attributed that effect primarily to the use of “trended data” in VantageScore models, while also recommending “a 40% increase in delinquency rate for loans where ‘lender choice’ results in the selection of the higher of two scores across a pool or portfolio.”
Fannie and Freddie charging the same credit fee for FICO and VantageScore 4.0 ultimately transfers underpriced risks to their portfolios. This carries notable implications for MBS investors, who will begin to see greater saturation in MBS pools of loans only underwritten with VantageScore.
“It will take time for VantageScore 4.0 levels to become meaningful in these pools, but I would expect investors to price in some amount of uncertainty once VantageScore 4.0 collateral reaches a critical mass,” added Valverde.
——
This article has been updated with industry comments.