Scotsman Guide Magazine

Qualified borrowers don’t always look qualified on paper

As income sources diversify, originators are adapting how they work with borrowers — and lenders are reassessing how they evaluate repayment ability

By Franco Terango

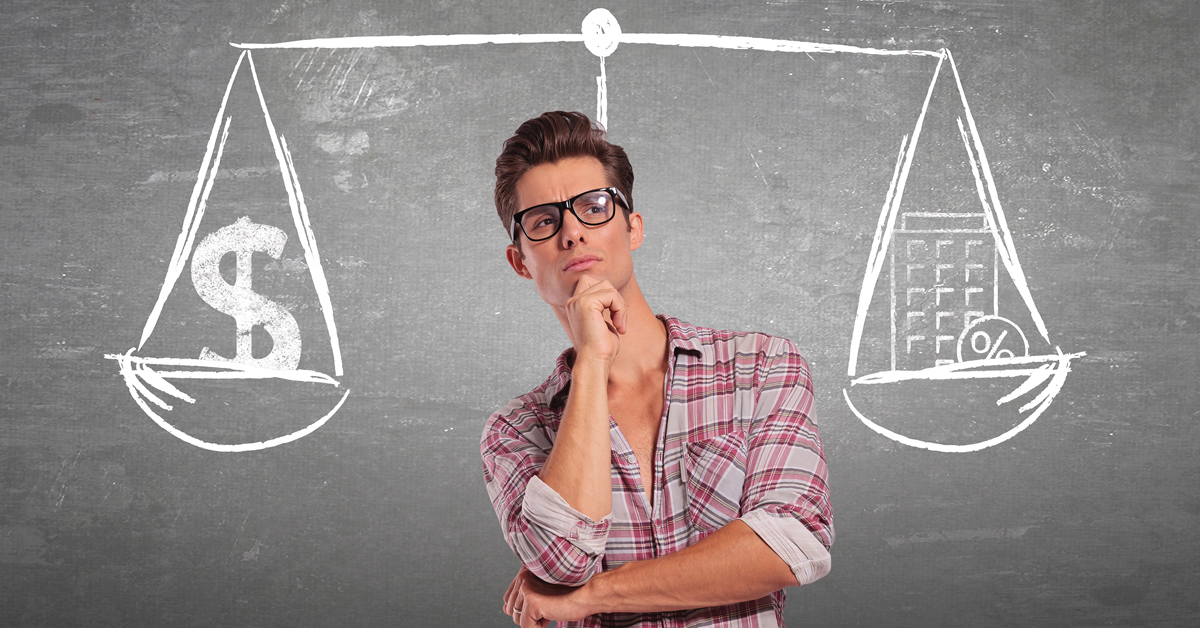
Consider a borrower earning over $150,000 annually, with strong credit, substantial savings and a consistent record of making payments on time. On paper, that is exactly what underwriting standards were built to recognize. But as income sources diversify, more of these borrowers no longer fit the conventional metrics lenders rely on. It is time for underwriting standards to catch up.
Now imagine that same person being told they do not qualify for the mortgage they want. Sadly, this is not uncommon. A general contractor may have significant business deductions that reduce taxable income. A software developer might receive much of their pay in restricted stock. A business owner may report income through a K-1 that doesn’t align with standard ...
You might also like...

Top Dollar Volume

Top FHA Volume

Top HELOC Volume

Most Loans Closed

Top Mortgage Brokers

Top Non-QM Volume

Top Purchase Volume

Top Refinance Volume

Top USDA Volume

Top VA Volume

Top Veteran Originators

Top Jumbo Originators

Top Women Originators

Top Overall

Top Wholesale

Top Retail

Top Non-QM

Top FHA

Top VA

Top Correspondent

Sign in to Scotsman Guide PRO

error: Content is protected !!

✓ You're all set!

Your account has been successfully claimed!
You’re now logged in and ready to go.

We found an account with this email.
Please log in or reset your password to continue.